



The price of copper was down 0.02% to US$9,838.50 ($15,029) a tonne on Wednesday (13 August) after edging close to its highest close in almost three weeks in anticipation of key economic data out of the US and China.
The three-month London Metal Exchange (LME) closing price of the metal is $9,840.50, with copper up 1.12% driven by anticipation of a rate cut from the Federal Reserve in September.
However, the Financial Times reports that
The global copper market remains in surplus despite strong price gains so far in 2025. Under “normal conditions” Oxford Economics notes says this would have limited price increases, however the threat of US tariffs have disrupted trade flows and distorted pricing.
“With those effects now fading, fundamentals are likely to reassert themselves, putting renewed downward pressure on prices,” the global independent economic advisory firm reports.
Copper prices were volatile early in Q2 2025 – from an all-time high in late March 2025 above US$11,000 a tonne – the price dropped to US$8,538 in early April as the US and China imposed tariffs on each other’s exports.
Increasing activity
Prices recovered as the tariffs tit-for-tat was largely reversed and consumers (predominantly from Asia) procured material at low prices.
Copper is emerging as a national security priority under US President Donald Trump’s current administration and long-term, analysts see a new chapter being written with the outlook remaining somewhat bullish, as reported by Mining.com.au.
Global demand grew 2.5% in Q1 2025 compared to the same quarter in 2024. The main growth contributors were China (up 3%), the US (up 7.4%), and the European Union (up 0.5%), as reported.
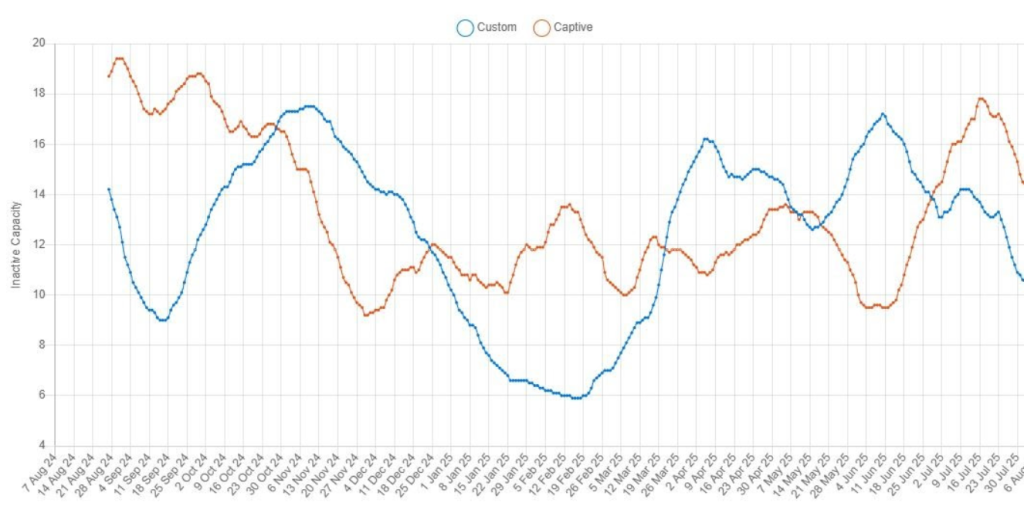
Meanwhile, the latest data from Earth-i’s SAVANT Global Copper Monitoring Index shows that smelting activity increased in July 2025 – as an average of 13.6% of global capacity was inactive – a fall of 0.4% from the prior month.
“In a reversal of the recent trend, it was strength in smelting activity in the ‘rest of world’ (RoW), which rose for the first time since January, that helped offset a weaker reading in China, where activity fell by 1.9%,” Earth-i reports.
“Nevertheless with inactivity for the month averaging only 9.8%, operators in the world’s second largest economy continue to defy punitive treatment and refining charges (‘TC/RCs’) compared to their counterparts in RoW, where inactivity still registered 16.4% over the month.
“It was also interesting to note the different behaviours between ‘custom’ smelters, those that do not get their concentrate feed from integrated mines upstream, and ‘captive’ smelters which do.”
Earth-i reports that activity at the former increased by 2.3% while the cohort of the latter decreased 2%, in part due to downtime at Zijin Mining’s (HKG:2899) 150 kT/a Qiqihar in Heilongjiang.
With an inactive capacity reading of 12.2% compared to 15.4% for captive plants, custom smelters were more active as a group for the first time since February, Earth-i says.
“We believe there are two main reasons for this. Firstly, captive smelters are more likely to be located in traditional mining jurisdictions, where employees take extended breaks for summer holidays. As such operators will plan for maintenance periods to coincide with reduced workforce availability,” Earth-i reports.
“Added to this is the tendency for custom smelters to increase production now before reducing activity in September – October to coincide with negotiations for next year’s benchmark TC/RCs, commonly known as ‘mating season’ in the industry, where it is in their interests to present the appearance of a ‘loose’ market and the appearance of sufficient concentrate availability.”
At a regional level, Europe had the biggest increase in activity, with inactive capacity series falling by 8.6% to 10.9%.
With Asia and Oceania’s inactive capacity series rising by 2.3% to 11.2%, Europe is now the most active region after China, while despite an improvement of 7.1%, North America has the highest inactive levels with an average of 31.6%.
Write to Adam Orlando at Mining.com.au
Images: Earth-i & Mining.com.au


