



Macmahon Holdings (ASX:MAH) expects the second half performance of FY23 to be stronger than the first half and has maintained its underlying EBIT(A) guidance of between $105 million to $125 million.
Revenue guidance has been increased to a range of $1.85 billion to $1.95 billion (previously $1.6 billion to $1.7 billion) primarily due to higher cost recoveries and the timing and finalisation of the Batu Hijau Phase 8 contract.
The mining services contractor’s order book remains robust at $5.6 billion of work in hand as of 31 December 2022 with executed and secured revenue for FY23 of around $1.8 billion (excluding short term churn work) underpinning the company’s full-year revenue target.
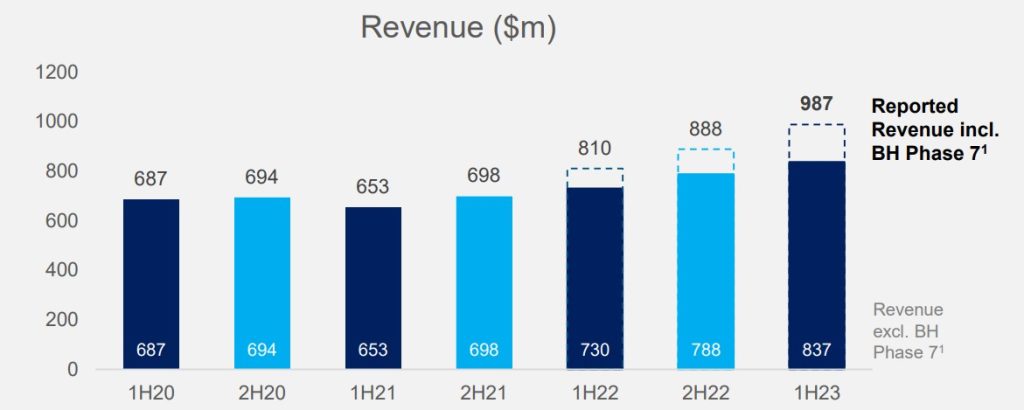
Macmahon reports that it has delivered another period of growth and solid operational performance in the first half of FY23 as it continues to execute on its client order book and effectively manage persisting industry wide cost and people resourcing challenges.
Commenting on the first half and the outlook for the company, Macmahon’s Chief Executive Officer and Managing Director Michael Finnegan says: “Macmahon has started FY23 on a strong footing with continued growth as we ramped up work on contract wins from last year and focused on orderbook delivery. We have grown our workforce in a demanding environment and have been working with our clients to effectively manage cost pressures.
“Macmahon has started FY23 on a strong footing with continued growth as we ramped up work on contract wins from last year and focused on orderbook delivery”
We were recently awarded $1.1 billion of new work for the Greenbushes lithium project, which delivers on Macmahon’s strategy to diversify into future facing / battery minerals. This was amongst other contact extensions and short-term work. We expect this positive momentum to continue into the second half with stronger earnings and operating cashflow performance relative to the first half.
We are also pleased to announce agreement of terms on the Batu Hijau Phase 8 extension, subject to Macmahon shareholder approval. The simplified contract will provide a guaranteed return on capital for our investment and an opportunity to earn half yearly management fees on meeting project KPI’s. Operating margins will improve under phase 8 with the elimination of zero margin pass through costs. Macmahon is well placed for a strong second half performance and will continue to effectively manage our capital position, our people requirements, and our costs.”
Revenue grew by 22% over the prior corresponding period to $987.2 million driven by activity across the group. As in prior periods, revenue included Batu Hijau cost recoveries and inflation driven cost recoveries in accordance with contract provisions.
Underlying EBITDA increased by 8% to $149.3 million with the commencement of new projects in 2H22 which have ramped up. The EBITDA margin of 15.1% (1H22 17.1%) reflected zero margin cost recoveries included in revenue both at Batu Hijau operations and from cost escalations across other projects.
Statutory NPAT increased to $23.3 million compared to $3.3 million in 1H22, however, underlying NPAT(A) decreased to $29.8 million compared to $31.7 million in 1H22.
Underlying operating cash flow generation was $105.5 million (1H22 $96.6 million) representing an underlying EBITDA conversion rate of 71%.
Capital expenditure (capex) for the first half was $100.7 million, significantly lower than the $152.7 million in 1H22 and comprised primarily of sustaining capex.
Net Debt/EBITDA of 0.83x and gearing of 29.9% reflect the higher working capital in the half and remain within our targets of below 1.0x and 30%, respectively. The stronger operating cashflow expected in the second half should see these metrics reduce at the full year. The balance sheet remains in a strong position to support the Company’s growth outlook with cash on hand of $196 million and cash plus available committed banking facilities of $271 million.
Macmahon reports the demand outlook remains positive with the tender pipeline increased to $10 billion and the primary focus remaining on effective people and capital management.
Write to Adam Orlando at Mining.com.au
Images: Macmahon Ltd


