



The Arctic is emerging as one of the world’s most strategically important mining frontiers, but geology alone will not determine its future.
According to GEM Mining Consulting CEO Juan Ignacio Guzman, the region’s vast endowment of critical minerals offers opportunities to strengthen global supply chains. Yet the greatest challenge lies in converting mineral potential into economically, socially, and environmentally viable mining projects.
As demand accelerates for the metals underpinning the energy transition, digital infrastructure, and defence and industrial manufacturing, Arctic regions host a mix of copper, nickel, cobalt, graphite, rare earths, platinum group metals, titanium, phosphate, and zinc deposits.
However, Guzman explains the Arctic should not be viewed simply as a warehouse of critical minerals. Instead, he describes it as a “decision frontier”, where every stage between discovery and production becomes more complex due to harsh climates, permafrost, limited infrastructure, logistics, Indigenous rights, and environmental sensitivity.
“That distinction is essential for mining investors and policy readers,” Guzman says.
“A resource is not a reserve. A reserve is not a mine. A mine is not a supply chain. A supply chain is not public wealth.”
The Arctic’s mining potential
While regions such as Fennoscandia and Nordic Arctic benefit from established rail networks, ports, renewable power, and skilled mining workforces, other jurisdictions face far greater barriers.
Northern Canada and Alaska boast world-class deposits but remain constrained by transport corridors, energy access, and Indigenous agreements. Greenland continues attracting global attention for its rare earths, graphite, and titanium potential, although strategic interest alone is unlikely to deliver operating mines.
Meanwhile, Russia’s substantial Arctic mining industry remains largely inaccessible to Western investors amid ongoing geopolitical tensions and sanctions.
Rather than pursuing every critical mineral project, GEM Mining believes exploration should focus on deposits capable of leveraging existing industrial districts, shared infrastructure, or valuable by-product recovery opportunities.
The consulting firm believes projects located near ports, rail infrastructure, and processing facilities stand a far greater chance of becoming commercially successful than isolated greenfield developments requiring billions in supporting infrastructure before production can begin.
Guzman also warns that responsible Arctic development requires far more than favourable economics.
“A credible Arctic project must therefore pay not only for mining, but for the conditions that make mining possible,” he says.
Feasibility filter
GEM Mining has developed what is described as a feasibility filter, requiring projects to demonstrate credible pathways across seven key areas before they can be considered strategic supply opportunities. These include proving market demand, technical viability, processing capability, logistics, community consent, environmental baseline data, and long-term mine closure planning.
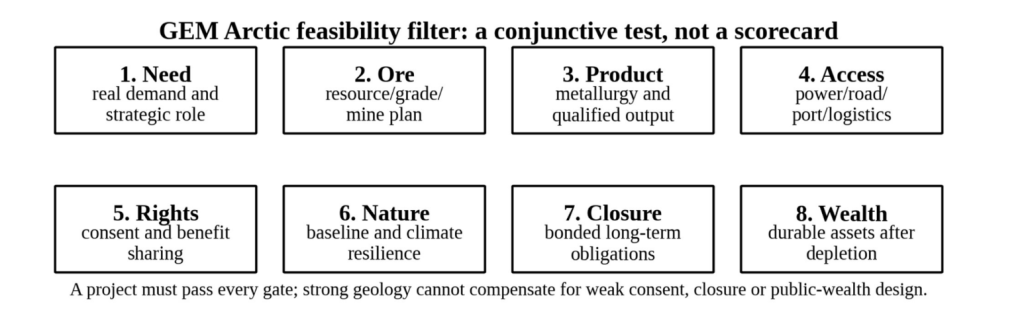
From an economic perspective, Arctic exploration should prioritise deposits that are richer, larger, better located, easier to process, or more strategic than comparable alternatives farther south.
The best candidates, GEM Mining says, are brownfield expansions, by-product recovery projects, deposits near tidewater or rail, and projects that can share power, ports, roads, data, and emergency responses with communities.
Remote bulk commodities require scale and logistics, while rare earth and graphite projects require downstream partners before they can be described as strategic supply.
From a social perspective, GEM Mining says the key requirement is legitimacy before acceleration. Legitimacy reduces risk by lowering the probability of litigation, delay, reputation loss, and moral failure.
Meanwhile, from an environmental perspective, the non-negotiable starting point is baseline knowledge. A project that cannot define natural background conditions, climate-resilient tailings and water management, funded closure, long-term monitoring, and enforceable responsibility is not yet financeable supply; rather, it is considered an unfunded public risk.
GEM Mining believes that the Arctic can make a meaningful contribution to supply chain resilience where geology aligns with infrastructure, processing capability, environmental stewardship, Indigenous partnerships, and long-term public benefit.
“The conclusion is not that the Arctic will save the energy transition,” Guzman says.
“Nor will the energy transition justify every project that claims to serve it. The more useful conclusion is that the Arctic can contribute strategically where geology, infrastructure, processing, rights, environmental design, and public wealth align.”
Write to Aaliyah Rogan at Mining.com.au
Images: GEM Mining Consulting


