



So far this year global M&A and initial public offerings activity figures are mixed although a brighter view of the likely path of monetary policy in the US, the UK, and eurozone supports a positive outlook during H2 2024.
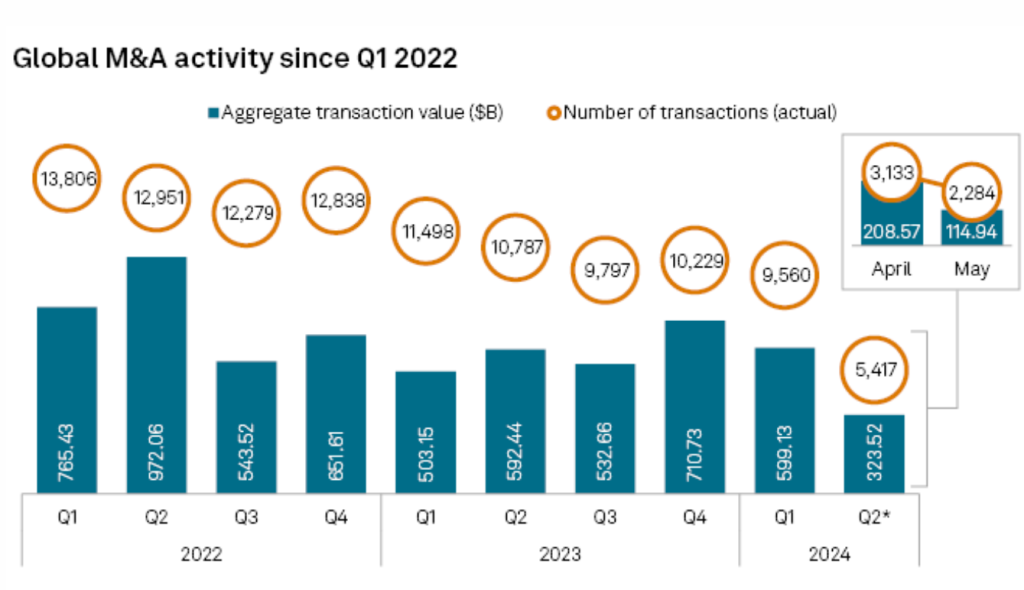
S&P Global Market Intelligence data shows 9,560 M&A transactions announced in Q1 2024 was almost 2,000 deals fewer than a year ago and the lowest recorded in two years. Despite this, the total value of deals improved year-on-year to US$599.13 billion ($900.96 billion) from US$503.15.
Compared to 2023, large M&A deals in the US, the UK, and globally have all increased so far in 2024.
At 296, the number of global IPOs in the first quarter was below the prior-year figure, while the total value of US$23.33 billion was closer to the US$24.16 billion booked in the first three months of 2023 for listings.
S&P Global reports that overall equity and debt capital market issuance activity in Q1 was stronger than a year ago in terms of both the number and value of transactions and April was a stronger month for activity across markets than May.
“Increased visibility into interest rates and expectations for a further narrowing of the valuation gap has boosted sentiment among private equity dealmakers, with more firms saying they are looking to divest assets in the first quarter of 2024,” EY’s latest sector survey shows.
The return of private equity firms after a retrenchment from markets over the past two years is viewed as essential to reviving M&A and IPO activity.
S&P Global reports the outlook for the rest of 2024 is poised for a steady increase in IPO activity across Europe with the UK lagging with market expectations suggesting the growth curve will continue and increase in 2025.
Write to Adam Orlando at Mining.com.au
Images: Unsplash & S&P Global


