



Global copper mine output is expected to rise just 3% in 2025 with the slight growth driven by capacity expansions at operating mines and the opening of new mines in Chile, the Democratic Republic of Congo (DRC), and China. Declining ore grades, limited access to funding, disruptions from energy access, regulatory complexity, inclement weather, and social unrest could hinder growth over the outlook period until 2026.
However, a modest rise of copper exploration activity in Australia and other copper-dominant regions such as Latin America are showing a glimmer of hope. Also at play is the Trump administration’s policies on tariffs and China’s robust copper-intensive EV market surging.
The Department of Industry, Science and Resources’ (DISR) December 2024 Resources and Energy Quarterly report shows Australian mine output in 2024–25 is forecast to grow to 800,000 tonnes — an increase of 1% compared to 2023–24. In 2025–26, output should rise slightly to reach 821,000 tonne – an 2.6% year-on-year increase
Global mine production reached 16.8 million tonnes in the first nine months of 2024 — a 2.4% increase compared to previous corresponding period in 2023. Mine output rose in Chile (up 2%), DRC (up 9.6%), and Indonesia (up 6.9%).
“This growth was due to improved output at major mines in Chile, recovery of constrained output in Indonesia and better power supply in the DRC. Peru’s output fell by 0.6% in the first nine months of 2024, driven by community blockades and weather issues,” DISR reports.
Looking for direction
Kincora Copper (ASX:KCC) and earn-in partner AngloGold Ashanti (NYSE:AU) have expanded an initial drilling campaign at the Nyngan Porphyry Project in New South Wales after hitting the targeted Macquarie Arc rocks. Nyngan is highly prospective for large scale porphyry related copper-gold.
Speaking to Mining.com.au on the state of the copper market, Kincora CEO Sam Spring says it’s “at a very interesting junction and looking for direction”.
“On one hand, we are in the traditionally seasonally strong period for the copper price post Chinese new-year holidays during a normal phase of restocking which will be a good indicator for underlying demand from the world’s largest consumer of copper,” Spring tells this news service.
“The copper price being up 3.8% week-on-week (the other) week, the highest weekly gain since September on face value is very positive. However, on the other hand, there is significant financial market positioning and speculation taking place in light of Trump’s new tariffs, and if they will or won’t include copper and wider implications to the economy.”
Tempest Minerals (ASX:TEM) last year began pivoting its strategy amid a subdued copper market. Managing Director Don Smith echoes Spring’s sentiments and reiterates his “usual fact-based narrative that the declining copper supply is a genuine threat to society” and the price should be a multiple of what it is.
“Doesn’t make sense. Some people are saying some of the big South American porphyry mines are starting to find more extensions which is offsetting the global deficit. I’m not convinced and definitely not convinced long-term,” Smith adds.
Kincora’s Spring, however, believes the current outlook for copper, and pricing for gold, is very favourable for Kincora at lease as it looks to undertake further asset level deals and partnerships for its copper-gold porphyry projects in New South Wales.
“The diversified majors, gold and copper majors are again generally looking for growth and rebuilding their exploration pipelines,” Spring says of copper’s outlook.

Upcoming copper plays
There’s a number of junior copper plays with exploration of pipelines in Australia and other copper-dominate regions such as Latin America.
Following a busy 2024 underpinned by gaining greater control of its flagship project, strengthening the balance sheet, and better-than-expected drilling results, Alma Metals (ASX:ALM) remains focused on resource growth and project optimisation.
In a recent interview with Shae Russell, Managing Director Frazer Tabeart spoke about the Briggs CopperProject in Queensland and the outlook for copper in 2025, stating Alma is bullish of the copper market.
“We’re long-term copper bulls. So, we lock that in mentally and then we’re unlikely to change our position on that. What this discovery shows is the scale potential that we’ve always talked about at Briggs,” Tabeart earlier this month said.
“And for the first time, we’re now actually testing part of that exploration target around an outside of the current resource. So, it’s adding that scale and scale in a long-term bull copper market in a project that’s got really good infrastructure.”
Alma Metals has confirmed a new porphyry discovery 300m southeast of the current Briggs resource. Looking ahead, Tabeart says Alma is focused on completing the mineral resource estimate, metallurgical testwork, and Scoping Studies, “setting the stage for an exciting 2025 as we progress toward unlocking the full potential of Briggs”.
Aruma Resources (ASX:AAJ) is gearing up for an aggressive exploration year. Managing Director Grant Ferguson recently told this news service the company is eyeing major copper-gold drilling in 2025.
Aruma has uncovered drill-ready targets at the Fiery Creek Project in the Mt Isa region of Queensland after completing a gravity survey. Once stakeholder and heritage surveys are completed, the company plans undertaking a phase one reverse circulation drilling program in Q2 2025.
Meanwhile, OD6 Metals (ASX:OD6) completed the acquisition of the Gulf Creek Copper Project, a volcanogenic massive sulphide (VMS) deposit located near the town of Barraba in New South Wales.
Gulf Creek was mined at the turn of the 20th century and once regarded as the highest grade copper mine (2% to 6.5% copper) in New South Wales until its closure due to weak copper prices in 1912. Very little exploration has occurred at the project in over 100 years, although OD6 is aiming to apply modern day exploration technologies.
According to Kincora’s Spring, M&A deals such as Gulf Creek will continue to be a key theme for producing assets and companies, adding that there will also be further earn-in and joint venture deals for earlier stag exploration projects and new mineral districts that offer tier-one scale potential.
“Last year a key deal in the earlier stage part of the sector were BHP (ASX:BHP) and the Lundin’s consolidating the Vicuna district, and only (recently) you have seen a very large, even earlier stage exploration deal between Ivanhoe Mines and Pallas Resources. I think we should expect to see this trend continue,” Spring tells Mining.com.au.
The renewed copper exploration focus in Australia comes as the Department of Industry, Science and Resources’ (DISR) December 2024 Resources and Energy Quarterly report shows Australian mine output in 2024–25 is forecast to grow to 800,000 tonnes — an increase of 1% compared to 2023–24. In 2025–26, output should rise slightly to reach 821,000 tonne – an 2.6% year-on-year increase.
One world, two Americas
Copper exploration is also picking up in other global copper regions on the back of subdued output in 2025, particularly in parts of South America.
Latin American focused copper-gold explorer Solis Minerals (ASX:SLM) has several workstreams underway in preparation to begin drilling in H2 2025 at the Cinto Project in Peru, as reported by Mining.com.au.
Extensive copper porphyry mineralisation has been identified in rock and channel sampling at Cinto. Solis is continuing to investigate Cinto’s potential by testing the unexplored low magnetic anomalies through mapping and rock geochemistry.
It’s welcome news for the company and Peru as the country in the first nine months of 2024 saw a 0.6% decline in copper output.
Flagship Minerals (ASX:FLG) has uncovered six new copper targets from a stream sediment survey at the Rosario Copper Project in Chile. Flagship intends undertaking follow-up activities, including rock chip sampling and stream sediment sampling, in many of the anomalous catchments. Drilling contractors have indicated start dates from mid to late March 2025. Flagship expects to conclude negotiations and enter formal contracts in the near-term.
Copper mine output in Chile rose by 2% in the first nine months of 2024, as output in the country’s major mines improved as the year progressed. Chile has faced a series of civil unrest in 2024. For example, in August workers at BHP’s (ASX:BHP) Escondida Copper Mine walked off the job after failing to successfully conclude wage negotiations.
Refined copper demand
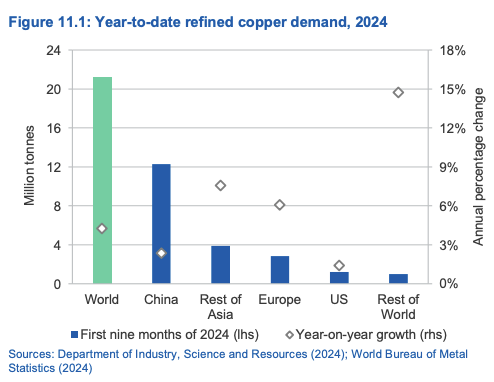
Globally, in the first nine months of 2024 refined copper demand was 21.2 million tonnes – 4.3% higher than the same period in 2023. This growth was broadly based across an increase in key copper-consuming markets China (2.4%), the US (1.4%), ex-China Asia (7.6%), and the European Union (6.1%).
Demand in the rest of the world surged by 15%, although it only accounted 900,000 tonnes of global demand over the same period.
World-wide demand is forecasted to grow by 1.8% in 2024 reaching 28 million tonnes, helped by rising consumption in EV manufacturing, AI-related data centres, and renewable energy infrastructure. Global demand is poised to rise by about 3% annually, reaching just under 29 million tonnes in 2025 and slightly less than 30Mt, in 2026.
Global smelting activity rose for the third month straight in January 2025, accelerating by 3%, according to geospatial intelligence company Earth-i’s Savant’s Global Copper Monitoring Index.
As reported by Mining.com.au, Earth-i reports the acceleration in smelting comes as inactivity averaged just 8.6%, the lowest figure since February 2023. Following November 2024’s 2.7% rise, copper smelting also registered a gain in December – this time 1.9%.
The collective 4.6% increase in activity over the two months to December (as deduced by a fall in inactivity from 16.1% in October to 11.5% in December) was the largest since January 2024 and before that February 2023, reflecting the consistent seasonal pattern driven by the timing of Chinese New Year.
US copper catalysts
According to DISR’s December 2024 Resources and Energy Quarterly, US copper demand is expected to grow through 2026, driven by investment in data centres and clean energy manufacturing.
According to the S&P Global’s 2024 US Datacentres and Energy Report, the country raised its data centre capacity by 10 gigawatts (GW) from 2017 to 2022. It is expected to add 50 GW of new capacity between 2023 to 2028.
US clean energy installations are anticipated to grow by over 25% in 2024, led by solar with 38 GW in the southeast and 29 GW in Texas. Solar systems require about 5.5 tonnes of copper per megawatt of power, while wind turbines require up to 4.7 tonnes.
Of such importance are data centres, Macquarie Asset Management is boosting its exposure in the US with a US$5 billion investment in next-generation digital infrastructure company Applied Digital (NADAQ:APLD), as reported by Mining.com.au.
Faraday Copper (TSX:FDY) is one such company eyeing new targets in the US, particularly within the Copper Creek Project area in Arizona which represents an opportunity to enhance value, after conducting over 30,000m of incremental drilling. A phase three drilling program is continuing within the project, focusing particularly on near-surface mineralisation in the American Eagle and Rum areas.
Trump and China
Driven by manufacturing, the energy transition, and construction, Chinese copper demand remains resilient. The government’s program subsidising the replacement of old cars and household appliances has also boosted copper consumption.
Kincora CEO Sam Spring tells this news service in terms of catalysts for forthcoming changes in 2025 there are “there are two obvious ones”.
“One, underlying demand from China; and two, Trump’s economic and political agenda,” Spring continues. Then there is always the potential for new supply shocks which given the nature of a pretty tight and balanced market could significantly influence pricing and sentiment.”
In an interview with Mining.com.au, Paul Harbidge, President and CEO of Faraday Copper says Trump’s tariffs policies is good for copper and good for its Copper Creek Project in Arizona.
“Well, firstly, I can say it’s certainly a bit of a rollercoaster ride … whether it’s tariffs being thrown around. But certainly, what we’re seeing is it’s good for mining – projects that have been stalled for many years are starting to progress,” the CEO says.
“You can certainly say the US is open for mining, which is exciting. And the US is also looking at unifying their critical metals list, bringing copper onto their list.”
On 13 February, copper was the latest metal to be lifted by the possibility it too could be the target of US tariffs coupled with tight supply. Futures were up 1.2% to US$4.69 ($7.47) a pound last Thursday morning. According to ANZ Senior Economist Adelaide Timbrell, following US President Donald Trump’s announcement of 25% tariffs on aluminium and steel, many traders believe copper is also in his sights.
Meanwhile, China’s EV market remains robust, with 1.1 million EVs and plug-in hybrids sold in the first nine months of 2024 — over 30% higher than sales in the same period in 2023. EVs are copper intensive, so transitioning from internal combustion vehicles to EVs and plug-in hybrids is also contributing to Chinese copper demand growth.
China was projected to achieve its 2030 renewable energy target of 1,200 gigawatts of wind and solar capacity by the end of 2024. This construction is copper intensive, boosting copper demand. However, additional solar and wind expansion may slow once targets are met.
Meanwhile, European Union copper demand rebounded by 6.1% in the first nine months of last year compared previous corresponding period, mainly driven by Germany and Italy. This was achieved despite ongoing weakness in the manufacturing and construction sectors.
Global mine output
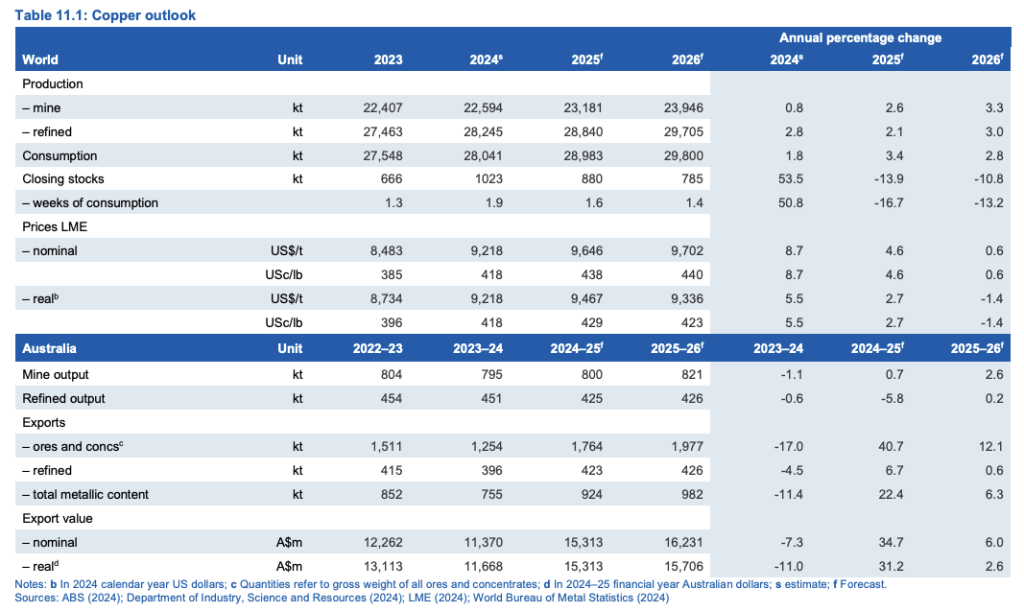
As mentioned, Australian mine output in 2024–25 is forecast to grow to 800,000 tonnes — an increase of 1% compared to 2023–24. In 2025–26, output should rise 2.6% year-on-year. As such, Kincora’s Spring says the medium to longer term outlook looks challenging on the supply side.
“When will we see a transition into a structural deficit is always hard to judge, but the fundamentals remain very compelling supporting a ‘when’ not ‘if’ scenario,” he adds.
DISR’s data backs Spring’s sentiment. Global mine output is expected to reach 23.2 million tonnes in 2025, an increase of just 3% compared to 2024, and 23.9Mt in 2026. This slight growth will be driven by capacity expansions at operating mines and the opening of new mines in Chile, the DRC, and China.
However, declining ore grades, funding scarcity, disruptions from energy access, regulatory complexity, weather events and social unrest could hinder growth over the outlook period.
Global mine production reached 16.8 million tonnes in the first nine months of 2024 — a 2.4% increase compared to previous corresponding period in 2023. Mine output rose in Chile (up 2%), DRC (up 9.6%), and Indonesia (up 6.9%).
“This growth was due to improved output at major mines in Chile, recovery of constrained output in Indonesia and better power supply in the DRC. Peru’s output fell by 0.6% in the first nine months of 2024, driven by community blockades and weather issues,” DISR reports.
Write to Adam Orlando at Mining.com.au
Images: DISR, Kincora, True North & Unsplash


