


Gunnison Copper (TSX:GCU) has filed a technical report for an updated preliminary economic assessment (PEA) on its namesake project in the US, outlining a ‘large-scale, long-life’ asset.
The Gunnison Copper Project has robust economics, including a post-tax net present value of US$2 billion ($2.89 billion) with an internal rate of return of 22.5% and a payback period of 3.9 years at a base case copper price of US$4.60 per pound.
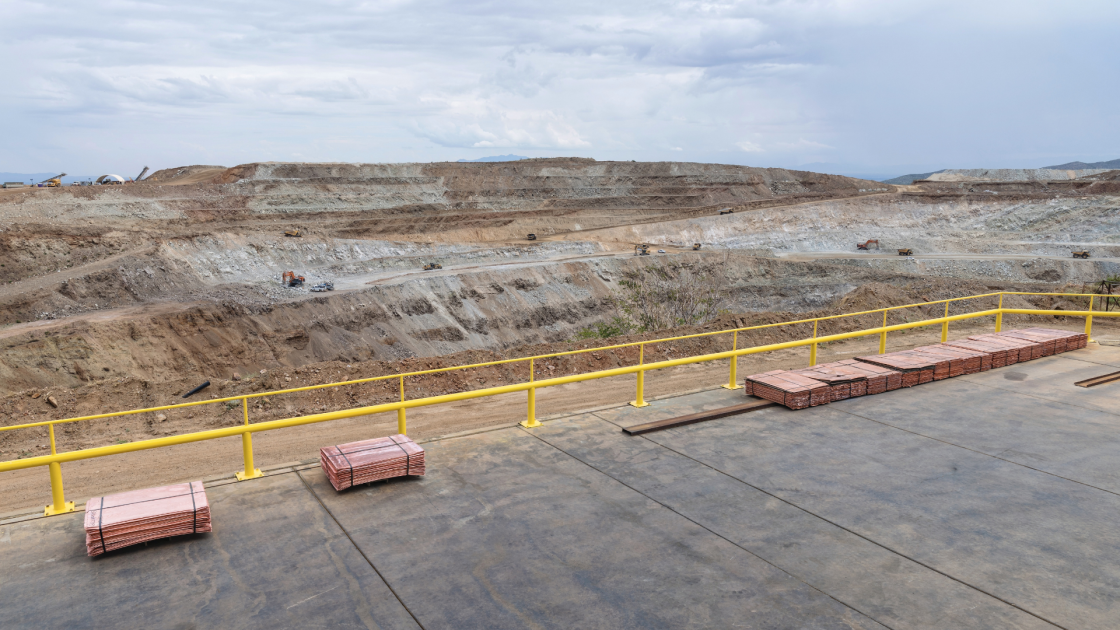
As previously reported, Gunnison is a conventional open-pit, heap leach operation. The project will produce 99.999% pure copper cathode to supply growing US demand from energy, data centre, manufacturing and defence supply chains.
Gunnison Copper says the straightforward mine plan consists primarily of oxide copper mineralised material with a life of mine material placed on the leach pad of 51 million tonnes @ 0.43% copper, including 25 million tonnes @ 0.85% copper from the Strong & Harris satellite deposit.
The project has an average annual copper cathode production of 174 million pounds for the first 15 years, which is equivalent to more than 11% of the current US domestic refined copper metal production from mineralised material. The total copper production is estimated to be 3.2 billion pounds over a 21-year period.
Cash costs total US$1.70, while sustaining cash costs is US$2 and all-in sustaining cash costs are US$2.05 per pound of copper produced are in the lower half of the cost curve for copper mines globally.
The Gunnison Project is located 65 miles east of Tucson, Arizona, on the southeastern flank of the Little Dragoon Mountains in the Cochise Mining District. The property is within the copper porphyry belt of Arizona.
Write to Aaliyah Rogan at Mining.com.au
Images: Gunnison Copper


