



The Australian Securities Exchange (ASX) advanced in early trade as investor excitement grew around the expected rate cut to be announced today (20 May).
The S&P/ASX200 climbed 60.1 points, or 0.72%, to 8,355.2 points by 10.30am (AEST).
Over the past five trading sessions, the index has gained 1.04% and is 3.02% below its 52-week high.
The ANZ tips a 0.25% rate cut, which will take the interest rate to 3.85% – the first time it has been below 4% since 2023.
Economist Sophia Angala says easing today is likely the “path of least regret”, given the uncertain global backdrop – notwithstanding the recent lift in equity markets – and encouraging inflation outcomes over the past two quarters.
“The most recent data on the consumer front suggests that the extent of the pick-up has softened relative to late 2024, and also relative to our (and we think the RBA’s) prior expectations,” she says.
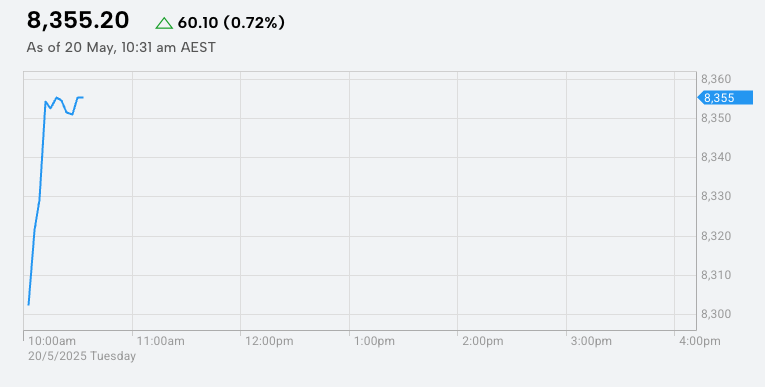
Seven of the 11 sectors climbed higher after the opening bell. Materials led the pack on a 0.3% tick higher. The financial sector edged up 0.04%, utilities lifted 0.03% and industrials advanced 0.02%.
Lithium miner Liontown Resources (ASX:LTR) recovered some of yesterday’s (19 May) losses to rise 4.41% to $0.71 in early trade, as did Pilbara Minerals (ASX:PLS), which gained back 3.2% to trade at $1.45.
However, uranium miners Paladin Energy (ASX:PDN) and Deep Yellow (ASX:DYL) lost ground today, both sliding around 1.24% to $5.59 and $1.20, respectively.
The S&P/ASX200 is Australia’s leading share market index and contains the top 200 ASX-listed companies in terms of market capitalisation, and accounts for about 80% of the country’s equity market. The index is designed to measure the performance of the 200 largest index-eligible stocks listed on the ASX by float-adjusted market capitalisation.
It is recognised as the institutional investable benchmark in the country.
Write to Angela East at Mining.com.au
Images: ASX & iStock


