
Iron ore is about as unglamorous as a commodity gets. It’s grey rock, dug out of the ground by the hundreds of millions of tonnes and turned into the steel that frames every building, bridge, and car on the planet. And yet a remarkably small number of mine sites are responsible for most of it. Australia and Brazil together handle roughly three-quarters of the world’s seaborne iron ore trade, and that concentration runs deeper still. Seven of the 10 largest individual mines in the world sit inside a single Australian region, and the other three all belong to one Brazilian company.
The rankings below come from GlobalData’s (LSE:DATA) mine-production database, using the most recent full year with verified production across all 10 sites, cross-checked against operator annual reports where those figures are public. Positions shuffle a little year to year, whether due to a cyclone through the Pilbara, a plant outage in Brazil, or a new pit ramping up. But the same handful of companies and the same two regions have dominated this list for the better part of two decades. What’s changed is less about who’s on it and more about how those operations get their ore out of the ground and onto a ship.
1. Serra Norte Mining Complex — Pará, Brazil
Operator: Vale (NYSE:VALE)
Type: Surface mining, hematite
Output: Approximately 102.8 million tonnes per annum (mtpa)
There’s a good story behind how this mine was found at all. In 1967, a team of geologists working for a Brazilian subsidiary of US Steel — searching for manganese, not iron — set their helicopter down on a bare hilltop in the Amazon Rainforest to refuel. One of them, Brazilian geologist Breno dos Santos, wandered off and started hammering at the rock. The reddish dust that came off wasn’t manganese; it was hematite, and extraordinarily pure hematite at that. That accidental find became the Carajás mineral province, now recognised as the richest known iron ore district on Earth.
Serra Norte, the complex that eventually grew out of that discovery, is the single largest iron ore mine in the world today, and it isn’t especially close to second place. Ore grades in the Carajás district average around 67% iron (Fe), roughly five percentage points above the typical Pilbara benchmark. This lets Vale compete on delivered cost into Asian steel mills despite shipping nearly 900km further than its Australian rivals. The complex sits within a federally protected national forest, which has shaped how it’s mined and expanded over the decades. Serra Norte is projected to keep producing at scale through to 2038.
2. Carajás Serra Sul S11D — Pará, Brazil
Operator: Vale
Type: Surface mining, hematite
Output: Approximately 76.67mtpa
S11D sits a short distance from Serra Norte within the same Carajás province, and it’s arguably the more interesting of Vale’s two entries on this list from an engineering standpoint. Rather than the fleets of haul trucks that move ore at every other mine on this ranking, S11D uses 37km of conveyor belts to shift material from pit to plant. Vale credits the ‘truckless’ design with cutting diesel consumption by roughly 77% and preserving around 90% of the native vegetation inside the project footprint. It’s a US$14.3 billion ($20.5 billion) bet that took the better part of a decade to plan and build before ramping up from 2016.
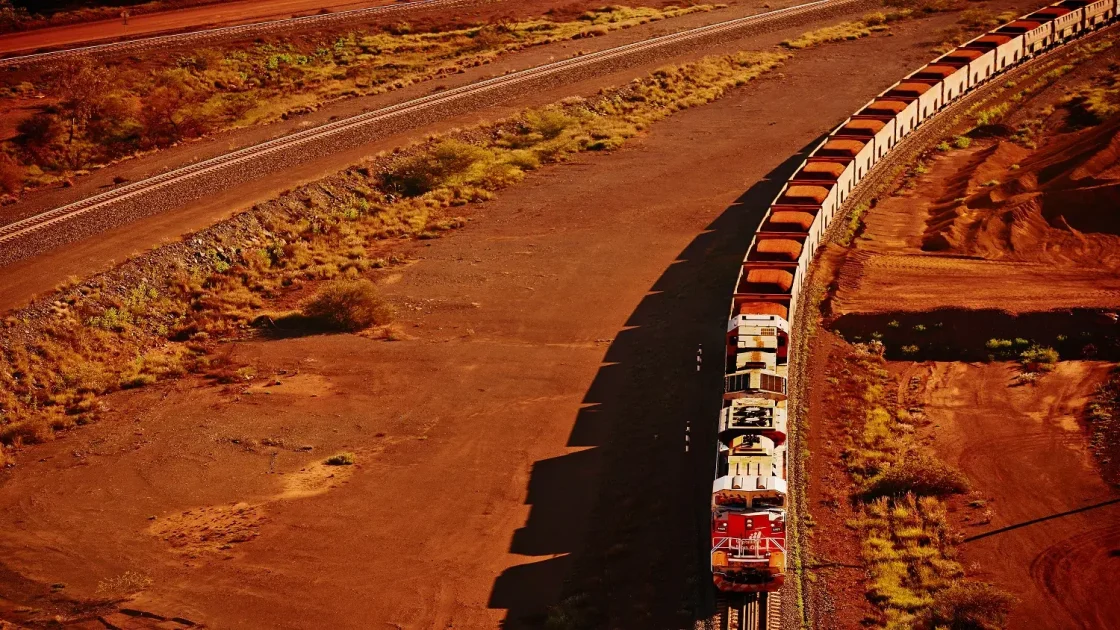
Both Serra Norte and S11D feed the same logistics chain: the 892km Carajás Railway. Opened in 1985, the railway hauls ore from Pará all the way to Vale’s dedicated deep-water port at Ponta da Madeira, near São Luís, for export. Combined, the two mines make Carajás the most productive iron ore province in the world on a per-site basis — ahead of the entire Pilbara, mine for mine.
3. Mt Newman Joint Venture — Pilbara, Western Australia
Operator: BHP Group (ASX:BHP)
Type: Surface mining, hematite
Output: Approximately 66.99mtpa
Mt Newman is where BHP’s Pilbara story really began. The joint venture was originally structured between BHP and partners including AMAX, CSR, Seltrust, and Mitsui-C. Itoh. Together, they built the town of Newman from scratch in 1966 to house the workforce, along with a 426km railway to the coast and new port facilities at Nelson Point, Port Hedland. The first trainload of ore left Newman on New Year’s Day 1969, and the first export cargo sailed for Japan on the Osumi Maru three months later. That year the operation shipped 6.45 million tonnes (Mt); today the same broad footprint, anchored by the Mount Whaleback pit, produces roughly 10 times that.
Ore at Mt Newman grades around 62.5% Fe, just above the seaborne benchmark. BHP’s ownership of the dedicated rail corridor keeps transport costs to an estimated US$5 per tonne, well below the US$7–10 industry norm for operations without their own private rail line. Mt Newman is expected to remain in production through to 2052, more than eight decades after the first geological surveys identified the deposit.
4. Jimblebar Hub — Pilbara, Western Australia
Operator: BHP
Type: Surface mining, hematite
Output: Approximately 66.8mtpa
Jimblebar sits close to Mt Newman and underwent a major expansion through the early 2010s that lifted it into the top tier of Pilbara producers. It was also one of BHP’s earliest large-scale bets on autonomous haulage, running trucks without drivers years before the practice became standard across the industry. The company has pointed to the site as evidence that automation delivers real productivity gains alongside a meaningful drop in safety incidents, rather than just a cost story for shareholders.
Like Mt Newman, Jimblebar feeds BHP’s integrated Pilbara rail and port network rather than operating as a standalone logistics chain, which is part of why BHP’s Western Australia Iron Ore division can move ore at some of the lowest unit costs in the industry. The site is planned to keep operating until around 2060.
5. Roy Hill — Pilbara, Western Australia
Operator: Hancock Iron Ore (Roy Hill Holdings)
Type: Surface mining, hematite
Output: ~61.6mtpa
Roy Hill is the odd one out on this list — the only top 10 mine not owned by Vale, BHP, Rio Tinto, or Fortescue. It’s majority owned by Hancock Prospecting (70%), the company built by Gina Rinehart, alongside a consortium of Japan’s Marubeni (TYO:800) with 15%, South Korea’s POSCO (NYSE:PKX) with 12.5%, and Taiwan’s China Steel (TPE:2002) with 2.5% — a structure that helped underwrite the roughly US$7.2 billion in debt financing needed to build the project from scratch. The deposit was first identified in the 1950s, but first ore wasn’t railed out until November 2015.
Like BHP and Rio, Roy Hill runs its own dedicated infrastructure end to end: a 344km heavy-haul railway and a purpose-built two-berth export terminal at Port Hedland rated to handle up to 64mtpa. The mine set a production and shipping record of 64Mt in FY2024, then shipped 61.6Mt in FY2025 despite record Pilbara rainfall and disruption from Tropical Cyclone Zelia — still comfortably enough to hold its place in the top 10. Ore grades run below the Pilbara benchmark, with a JORC reserve averaging around 59.3% Fe, but Roy Hill’s scale and its own low-cost rail-and-port model let it compete on delivered cost regardless.
6. Mining Area C (MAC) Hub — Pilbara, Western Australia
Operator: BHP
Type: Surface mining, hematite
Output: Approximately 58.47mtpa
Mining Area C carries the longest projected mine life of anything on this list, underpinned by reserves estimated above 2 billion tonnes (Bt) — the kind of resource base that lets a mining company plan in decades rather than years. It’s also one of the more environmentally forward-looking sites in BHP’s portfolio: a solar farm paired with battery storage supplies a meaningful share of the mine’s daytime power needs. It forms part of a broader push across the Pilbara to trim diesel use on sun-drenched sites that, frankly, seem almost designed for solar.
The MAC Hub shares processing and transport infrastructure with neighbouring BHP operations, which helps explain why a mine of this scale can run with a relatively lean standalone footprint. Current projections have it in production until 2067, giving it the longest projected mine life of any operation in this top 10. It’s a reminder of just how much resource still sits beneath the Pilbara’s red dirt.
7. South Flank — Pilbara, Western Australia
Operator: BHP
Type: Surface mining, hematite
Output: Approximately 80mtpa
South Flank is the newest mine on this list by a wide margin, and its backstory is really about what it replaced. BHP’s Yandi mine — not to be confused with Rio Tinto’s (ASX:RIO) nearby Yandicoogina operation (more on that mix-up below) — had been supplying premium, low-phosphorus direct-shipping ore for decades, but was running out of economic reserves. South Flank, comprising the Grand Central, Vista Oriental, and Highway deposits within the same Marra Mamba iron formation, was built specifically to take over that role. First ore came out of the ground in May 2021, following a US$3.6 billion construction program that began in 2018. Notably, the project was completed on time and on budget — not something every mega-project in this industry can claim.
It was also designed from day one as a ‘digital-first’ operation: autonomous trucks and drills, and a dense network of sensors feeding real-time ore-quality data into blending decisions, so the plant can hold tight to the grade specifications customers pay a premium for. It’s the largest new iron ore processing facility built in Australia in half a century.
8. Greater Tom Price — Pilbara, Western Australia
Operator: Rio Tinto (ASX:RIO)
Type: Surface mining, hematite
Output: Approximately 51.62mtpa
Tom Price is where the whole Western Australian iron ore industry effectively started. The Commonwealth government lifted its export embargo on iron ore in 1960 — a policy dating back to fears of shortages during World War II — and Rio Tinto commissioned Tom Price as its first Pilbara mine in 1966, three years before Mt Newman shipped its first cargo. Sixty years on, it’s still a top-10 global producer, kept alive by the Western Turner Syncline extension and an ongoing modernisation program that’s stretching mine life out toward 2035.
It would be an incomplete picture not to mention that Rio Tinto’s Pilbara operations, broadly, have carried a heavier reputational weight since May 2020, when the company legally destroyed the Juukan Gorge rock shelters during an expansion roughly 60km from Tom Price. The site had more than 46,000 years of continuous Aboriginal occupation and was sacred to the Puutu Kunti Kurrama and Pinikura people. The fallout cost Rio Tinto’s chief executive and two senior executives their jobs and pushed sweeping reforms to how the company handles Aboriginal heritage across all its Pilbara sites, Tom Price included.
9. Kings Valley — Pilbara, Western Australia
Operator: Fortescue Metals Group (ASX:FMG)
Type: Surface mining, hematite
Output: Approximately 51.29mtpa
Kings Valley opened in March 2014 as the capstone of Fortescue’s US$9.2 billion Pilbara expansion. It now forms part of the Solomon Hub alongside the Firetail and Queens Valley mines — together capable of around 75mtpa. Sitting roughly 60km north of Tom Price, on the traditional land of the Yindjibarndi people, the hub has also been the subject of a long-running native title compensation dispute between Fortescue and the Yindjibarndi Aboriginal Corporation, one of the more closely watched Indigenous land-rights cases in the sector.
The ore itself is where Fortescue’s story diverges from its bigger rivals: Kings Valley grades around 57.5% Fe, noticeably below the 62% benchmark most buyers price against. Rather than accept the discount, Fortescue sank roughly US$1.3 billion into a beneficiation plant that crushes, screens, and magnetically separates the ore before it ever reaches port — upgrading a lower-grade deposit into a product that can compete on quality with higher-grade Pilbara peers.
10. Yandicoogina — Pilbara, Western Australia
Operator: Rio Tinto
Type: Surface mining, channel iron deposit (CID)
Output: Approximately 51.1mtpa
Here’s where things get genuinely confusing for anyone new to the Pilbara. Yandicoogina, often shortened to ‘Yandi’, is a Rio Tinto mine about 95km north-west of Newman. It sits only a few kilometres from an entirely separate, unrelated BHP deposit that was also called Yandi, and which South Flank was built to replace (see the number six listing above). Two different companies, two different mines, one very similar name, decades of confused conversations at industry conferences.
Rio Tinto’s Yandicoogina is geologically distinctive in its own right: rather than the hard hematite typical of most Pilbara mines, it’s a channel iron deposit. Essentially an ancient riverbed, the area is part of the roughly 50km Marillana-Yandicoogina-Weeli Wolli paleochannel system, where iron-rich material accumulated as loose, pisolitic (‘pea-like’) pellets rather than solid rock. Mining began at the Junction Central pit in 1996 and expanded through Junction South East in 2006 and Junction South West in 2012. It was also Rio Tinto’s first fully autonomous mine, tightly integrated with AutoHaul — the company’s driverless heavy-haul rail network — and it’s expected to stay in production until around 2039.
Why this ranking is about to get more interesting
Four companies — Vale, BHP, Rio Tinto, and Fortescue — control nine of the world’s 10 largest individual iron ore mines, and that concentration has held for the better part of two decades. But the picture is starting to shift, and it’s worth watching closely rather than assuming the status quo holds forever.
The Simandou Project in Guinea, backed by Rio Tinto alongside a consortium led by Chinalco (SSE:601600), shipped its first ore in December 2025 and is targeting between 15–20Mt in 2026. That’s a fraction of what any mine on this list produces, but its long-term design capacity, once fully ramped up, could see it rank among the world’s largest within a few years. Simandou is widely regarded as the most significant new entrant to high-grade iron ore supply in decades, and it’s not Australian or Brazilian, which alone makes it worth watching.
Meanwhile India, led by state-owned NMDC (NSE:NMDC), is expanding output quickly enough that analysts expect it to be the single biggest driver of global supply growth in 2026. Total global iron ore production is forecast to grow around 4.5% this year, pushing the world total toward 2.7Bt.
None of these will displace the current top 10 any time soon. These are multi-decade assets underpinned by tens of billions of dollars in rail, port, and processing infrastructure that simply can’t be replicated overnight. But the next real reshuffle in this list is far more likely to come from a brand-new project like Simandou than from further expansion at an existing site.
Frequently asked questions
1. What is the largest iron ore mine in the world?
Vale’s Serra Norte Mining Complex in Pará, Brazil, is the world’s largest single iron ore mine, producing an estimated 102.8Mt in the most recent full production year.
2. Which country has the most large iron ore mines?
Australia, with seven of the world’s 10 largest individual iron ore mines — all located in Western Australia’s Pilbara region.
3. Which company owns the most top-10 iron ore mines?
BHP operates four of the 10 largest mines (Mt Newman, Jimblebar, Mining Area C, and South Flank), the most of any single company, followed by Vale and Rio Tinto with two each and Fortescue with two.
4. Why is Brazilian iron ore graded higher than Australian ore?
Vale’s Carajás deposits in Brazil typically grade around 67% Fe, compared with a seaborne benchmark of 62% Fe common across much of the Pilbara. Higher-grade ore requires less processing at the steel mill and commands a price premium.
5. Will Simandou change the ranking of the world’s largest iron ore mines?
Not immediately. Simandou in Guinea only began shipping ore in December 2025 and is targeting 15–20Mt in 2026 — well below the roughly 47–103Mt produced by mines on this list. As the project ramps toward its multi-hundred-million-tonne long-term capacity over the coming years, however, it is widely expected to eventually rank among the world’s largest.
Image Credit: bhp.com