
Comparing bullion, ETFs, and ASX-listed gold companies.
Context and background
Gold has preserved purchasing power across centuries and market cycles. In the modern era, Australian investors have more ways to access it than at any point in history. These include physical coins and bars held in a vault, exchange-traded funds (ETFs) trading on the Australian Securities Exchange (ASX), and shares in the companies that dig it out of the ground. Each method delivers a different kind of exposure, carries different costs and risks, and suits a different kind of investor.
Understanding the distinctions between these options is more useful than simply knowing that gold exists as an investment. The method you choose determines what you actually own, how directly your returns track the gold price, and what can go wrong.

Physical gold: coins, bars, and certificates
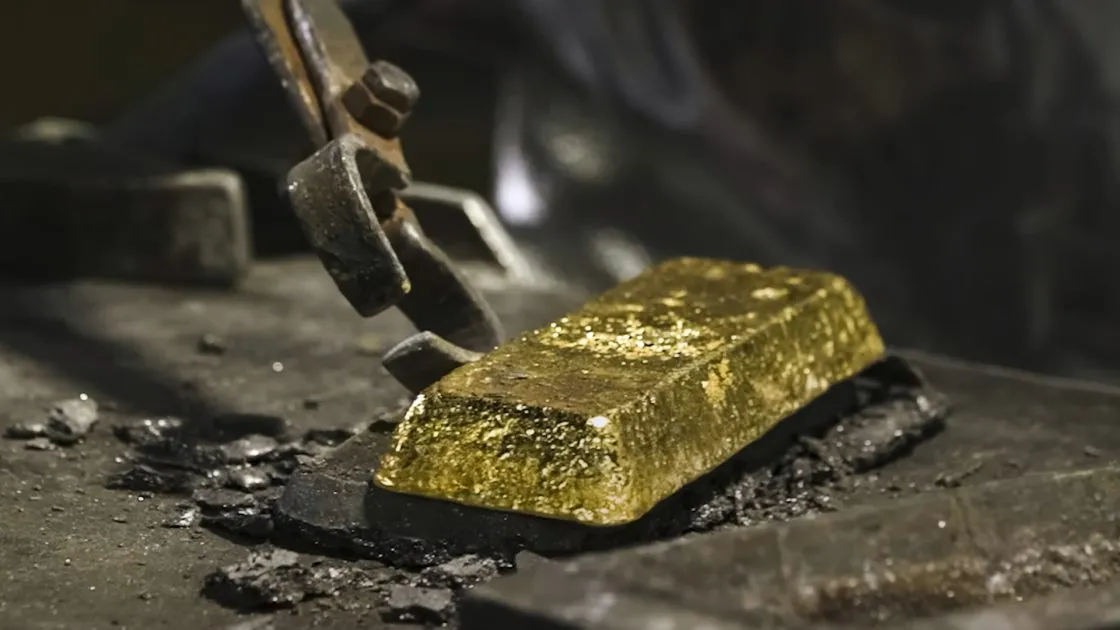
Buying physical gold means owning the metal directly. That could mean a coin, a cast bar, or a minted bar held either in your possession or in a vault on your behalf. This is the oldest and most literal form of gold ownership, and it remains the preferred approach for investors who want zero counterparty risk. The gold exists, it belongs to you, and its value doesn’t depend on the solvency of any financial institution.
The trade-offs are practical rather than conceptual. Physical gold has to be stored securely, which means either a home safe with insurance, a bank safe deposit box, or a specialist vault provider. Storage and insurance costs typically run between 0.1–0.5% of asset value per year, which compounds meaningfully over time. The buy-sell spread — the difference between the price at which dealers sell and the price at which they buy back — generally ranges from 1–5% depending on the product and volume. Coins and smaller bars carry higher premiums per ounce than larger bars. Liquidity isn’t an issue for standard investment-grade products, but the transaction process is slower and more manual than selling shares.
The Perth Mint in Australia is one of the world’s leading bullion refiners and dealers, and its products carry international recognition. The mint operates under a government guarantee enshrined in the Gold Corporation Act 1987, and the Western Australian Government, which owns the mint, guarantees its liabilities.
This guarantee applies to the institution’s obligations, not to the gold price itself. The Perth Mint went through a period of regulatory scrutiny relating to anti-money-laundering compliance, which was resolved in July 2025 when the Australian Transaction Reports and Analysis Centre (AUSTRAC) released it from a court-enforceable undertaking following confirmed remediation. Its Good Delivery accreditation with the London Bullion Market Association (LBMA) was retained throughout. This is worth knowing as background, particularly for investors considering the mint’s depository or certificate products.

Gold ETFs: Paper gold on the ASX
A gold ETF is a managed fund listed on the ASX whose units track the price of gold. Buying ETF units through a standard brokerage account gives investors gold price exposure without the cost and friction of storing physical metal. For most retail investors, it’s the most practical entry point.
The most important structural detail to understand before buying a gold ETF is whether the fund holds allocated or unallocated gold.
Allocated means specific, identifiable bars are set aside for the fund — individually numbered, weighed, and regularly audited. The gold is legally segregated from the ETF provider’s own assets, meaning it sits outside the provider’s balance sheet and can’t be used to satisfy the provider’s creditors if the provider becomes insolvent. This is the structure most investors assume they’re getting, and it’s the strongest form of physical backing an ETF can offer.
Unallocated means a gold credit is held against a pool of gold rather than against specific bars. The investor’s claim is on the institution holding the gold rather than on specific metal. Unallocated structures typically carry lower fees because they’re cheaper to operate — gold held in an active refinery or in transit is unallocated, for example — but they introduce a degree of counterparty risk that allocated structures don’t.
This is why one major Australian gold ETF, the Perth Mint Gold Structured Product (ASX:PMGOLD), specifically relies on the Western Australian Government guarantee as a structural feature. The ETF uses an unallocated structure backed by gold at The Perth Mint.
Beyond the allocated versus unallocated distinction, ASX-listed gold ETFs differ in two other meaningful ways.
The first is currency exposure. Most gold ETFs provide unhedged exposure, meaning returns in Australian dollars reflect both the movement in the gold price and the AUD/USD exchange rate. When the Australian dollar falls against the US dollar, unhedged gold ETFs deliver amplified returns in AUD terms, and vice versa. Currency-hedged gold ETFs eliminate this effect, tracking the gold price in AUD terms more closely, which is useful for investors who want pure gold price exposure without the currency overlay.
Storage location is the second. Some ASX gold ETFs hold their physical gold in London vaults under LBMA custody arrangements; others hold gold domestically at The Perth Mint. For most investors, this is a second-order concern, but it’s worth knowing where the gold is held. Product disclosure statements specify its location.
Management fees for ASX gold ETFs generally range from around 0.15–0.60% per year, deducted by gradually reducing the gold entitlement per unit over time. These are significantly lower than the all-in costs of holding physical gold directly for most retail investors. One practical limitation of ETFs is that ordinary retail unit holders generally don’t have a straightforward way to convert their units into physical bars. Some larger institutional investors can, under specific conditions, but this isn’t a realistic option for a standard brokerage account holder.
ASX-listed gold companies: Shares in the miners
Buying shares in an ASX-listed gold mining company is a fundamentally different proposition from buying gold itself. The share price reflects the company’s profitability, management quality, production costs, reserve life, development pipeline, balance sheet, and operational execution — as well as the gold price. This means gold shares can significantly outperform the gold price when conditions are favourable, and significantly underperform it when they aren’t.
The relationship between gold shares and the gold price runs through margins. A gold producer with operating costs of $1,500 per ounce earns $500 per ounce profit when gold trades at $2,000, and $1,000 per ounce profit when gold trades at $2,500 — a 25% rise in the gold price doubles the profit margin. This operating leverage is why gold shares tend to move more dramatically than the gold price itself, in both directions.
What this means in practice is that gold shares introduce a layer of company-specific risk that physical gold and ETFs don’t carry. A mine can experience production problems, cost blowouts, geological surprises, or permitting delays that cause the share price to fall even while the gold price rises. Management decisions — capital allocation, hedging policy, acquisition strategy — affect returns independently of what gold does. For investors who are genuinely confident in a particular company’s operations and management, that leverage can be attractive. For investors who primarily want gold price exposure, it’s an additional source of risk without a guaranteed additional return.
The ASX has a deep pool of gold companies across the size spectrum. This includes large diversified producers with multiple operating mines and significant reserve bases, single-project developers awaiting construction decisions, and early-stage explorers with no revenue and no certainty of ever producing an ounce. Each sits at a different point on the risk-return curve, and the appropriate research process differs substantially across these categories.
Gold companies can also pay dividends, which neither physical gold nor gold ETFs do. Several larger ASX gold producers have established dividend policies, which means gold shares can generate income as well as capital growth in a rising gold price environment.

How currency affects all three
Investing in physical gold, gold ETFs, or gold shares carries AUD/USD currency exposure to some degree because gold is priced globally in US dollars. When you buy physical gold from an Australian dealer, the price you pay in AUD reflects the prevailing exchange rate. When you sell, it does again. The same applies to unhedged ETFs. Gold shares sit slightly differently — Australian gold producers earn revenue in USD but pay many of their costs in AUD, so a falling Australian dollar is generally positive for their margins even before any movement in the gold price.
Currency-hedged ETFs are the only structure that actively removes this exposure, at the cost of the hedging fee built into the management expense ratio. Whether that’s worth it depends on your view of the Australian dollar and how much you want gold to behave as a pure commodity rather than a commodity-plus-currency position.
Tax treatment
All three methods are subject to Australian capital gains tax (CGT) on disposal, with the standard 50% CGT discount available for assets held longer than 12 months. Physical gold and gold ETFs are treated as investment assets for CGT purposes. Dividends from gold company shares are treated as ordinary income and may carry franking credits depending on the company’s tax position. This article provides general context only; individual tax circumstances vary, and a tax adviser is worth consulting before making investment decisions.
Which approach suits which investor
Physical gold suits investors who want direct, unmediated ownership of the metal, have a long holding horizon to amortise storage and transaction costs, and place significant weight on holding an asset with no counterparty risk.
Gold ETFs suit investors who want efficient, low-cost gold price exposure through a standard brokerage account, without the friction of physical storage. The allocated versus unallocated distinction and the currency hedging question are the two decisions worth understanding before choosing between products.
Gold shares suit investors who want leveraged gold exposure and are willing to conduct company-specific research, accept operational risk, and tolerate more volatile returns than the gold price itself would produce.
Many investors use a combination of all three, treating physical gold or ETFs as the stable core of their gold allocation and using gold shares for additional exposure when they have conviction in a specific company.
Conclusion
Gold is accessible to Australian investors in ways that are genuinely different in structure, risk, and return profile. Physical bullion, ASX-listed ETFs, and shares in gold mining companies all provide exposure to the gold price, but what you own, how your returns are generated, and what can go wrong differ substantially across the three approaches. Understanding those differences is the starting point for deciding how gold fits into a broader investment portfolio.
This article is for educational purposes only and does not constitute financial or tax advice. Investors should seek independent professional advice before making investment decisions.
Write to Tyler Jefferson at Mining.com.au
Images: Wikimedia Commons & Unsplash