
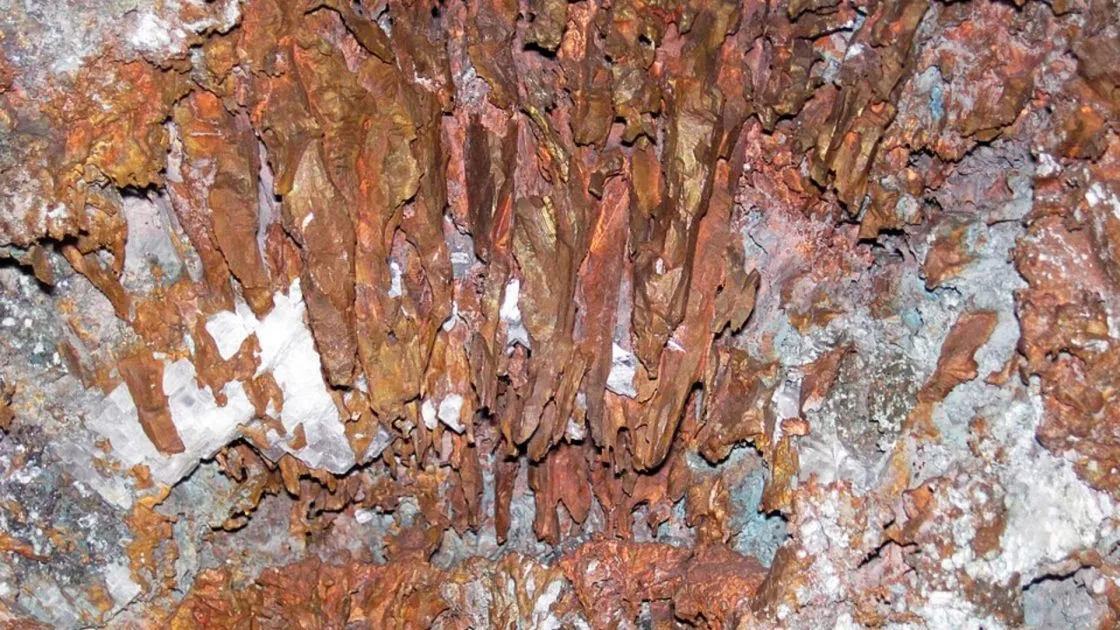
Porphyry systems and the world’s major copper regions.
Context and background
Understanding where copper comes from geologically and why it concentrates where it does is useful background for following exploration announcements, interpreting drill results, and making sense of why certain regions dominate global copper supply.
The short answer is that copper deposits are not randomly distributed. They cluster in specific geological settings shaped by ancient tectonic processes, and the most important of these settings by a wide margin is the porphyry system. Porphyry deposits account for the majority of the world’s copper production, and most of the large mines that matter to global supply sit within them.
What a porphyry deposit actually is
The word ‘porphyry’ refers to a type of igneous rock with large crystals set in a finer-grained matrix, a texture that forms when magma cools in two stages. In a copper mining context, ‘porphyry’ has come to describe a specific class of ore deposit that forms around these intrusive rock bodies, typically large, low-grade, and often carrying copper alongside gold, molybdenum, or silver.
What distinguishes porphyry deposits from other copper deposit types is their sheer scale. Individual porphyry systems can contain hundreds of millions, sometimes billions, of tonnes of mineralised rock. The grades are typically low, often less than 1% copper, but the volumes are enormous, which makes them economic to mine at scale using large open-pit methods. A single major porphyry deposit can sustain a mining operation for decades.

How porphyry deposits form
The vast majority of economically significant porphyry systems form in regions where oceanic crust is forced beneath continental or island arc lithosphere. This is the tectonic process where one of Earth’s crustal plates dives beneath another, typically where an ocean plate meets a continental plate. The Andes in South America are a classic example. The Nazca Plate has been subducting beneath the South American continent for tens of millions of years, and this process is directly responsible for the copper-rich geology of Chile and Peru.
The mechanism works roughly like this: as the subducting oceanic plate descends into the mantle, it releases water and other volatiles. These fluids lower the melting point of the overlying mantle wedge, generating metal-enriched magmas. Those magmas rise through the crust, and under suitable conditions intrude into the upper crust where they cool, crystallise, and release hot, pressurised fluids carrying dissolved copper and other metals. These fluids move outward through fractures in the surrounding rock, and as they cool and react with the wall rock, copper minerals precipitate out and concentrate.
The result is a deposit with a distinctive internal structure. The potassic zone at the core, characterised by secondary feldspar and biotite, typically hosts the highest grades of copper and gold. Around it sits the phyllic zone, dominated by quartz and sericite with abundant pyrite. Further out is the argillic zone, where feldspars are altered into clay minerals, and beyond that the propylitic zone at the margins, marked by chlorite and epidote.
Exploration geologists use these alteration patterns as a map, identifying the outer zones on the surface that can indicate that a mineralised core exists at depth, even before a drill bit has confirmed it.
One additional factor worth knowing: porphyry copper deposits typically form at depths of 1.5–4km and need to be exposed at the surface through uplift and erosion in order to be economically mined. Deposits that formed but were never uplifted, or were eroded away entirely, are lost. The ones that survive and are accessible to mining represent a specific geological window: deep enough to have formed, shallow enough now to reach.
Other copper deposit types
Porphyry systems dominate global copper supply, but they are not the only deposit type that matters.
Sediment-hosted copper deposits, sometimes called ‘stratabound’ or ‘SEDEX’ deposits, form where copper-bearing fluids migrate through sedimentary basins and precipitate in specific rock layers. These deposits tend to have higher copper grades than porphyries but smaller overall size. The Central African Copperbelt, stretching across the Democratic Republic of the Congo (DRC) and Zambia, is the world’s most important example of this type, and it hosts some of the highest-grade copper deposits mined anywhere today.
Volcanogenic massive sulphide (VMS) deposits form at or near ancient seafloors where hydrothermal vents concentrated metals. They often carry copper alongside zinc, lead, and gold in relatively compact, high-grade lenses. Olympic Dam in South Australia is a large and unusual copper deposit that doesn’t fit neatly into standard classifications. It’s an iron oxide copper-gold (IOCG) deposit, a rarer type associated with deeply sourced fluids rather than subduction-related magmatism, and it hosts one of the largest copper-uranium-gold resources in the world.
The world’s major copper regions
Chile alone produces more than 28% of the world’s copper supply, making it the dominant force in global copper production by a substantial margin. Chile holds 180 million metric tonnes of copper reserves, nearly as much as Australia and Peru, the next two largest reserve holders, combined. The country’s copper geology is concentrated in the Atacama Desert and the Andean cordillera of northern Chile, where a chain of giant porphyry deposits runs roughly north-south along the line where the Nazca Plate has been subducting for millions of years. Escondida, in the Antofagasta region, is the single largest copper mine in the world by output. Codelco, the state mining company, operates several of the other major mines including Chuquicamata and El Teniente.
The DRC produced 3.2 million metric tonnes of copper in 2025, accounting for nearly 14% of global output, having risen rapidly to become the world’s second-largest producer. The DRC’s copper comes from the Central African Copperbelt rather than porphyry systems. The region hosts high-grade, sediment-hosted deposits in Katanga Province, including Kamoa-Kakula, now one of the highest-grade large copper mines operating anywhere in the world. The DRC’s rise has been dramatic, driven largely by Chinese-backed investment, but the country carries significant political and operational risk that investors in DRC-focused companies price carefully.
Peru ranks third globally, with production anchored by large porphyry deposits in the Andes including Cerro Verde, Las Bambas, Antamina, and Quellaveco. Peru holds roughly 100 million tonnes of reserves, comparable to Australia and second only to Chile. Recurrent community protests along transport corridors and at mine sites have periodically disrupted production, making social licence an ongoing operational consideration.
Beyond the top three, China, the United States, Russia, Zambia, Australia, Indonesia, and Mexico each contribute meaningfully to global supply. Chile, the DRC, and Peru alone account for nearly half of global supply, a concentration that means disruption in any one of these jurisdictions can move global copper prices quickly.
The Carlin Trend’s copper operations in Nevada, Indonesia’s Grasberg mine — one of the world’s largest — and Australia’s Olympic Dam, along with emerging tier-one projects in Queensland and Western Australia, round out the global picture.

What this means for exploration
The geological logic of porphyry formation gives exploration a directional framework. Regions with ancient subduction histories along continental margins — the Andes, the North American Cordillera, the Pacific Ring of Fire, parts of Central Asia — are where porphyry deposits are most likely to occur. Explorers looking for new discoveries concentrate their efforts in these belts, particularly in areas where surface geology shows the alteration patterns associated with porphyry systems.
Finding a new porphyry deposit of the size needed to support a major mine is genuinely difficult. The large, accessible systems in the best-known belts have mostly been found. New discoveries increasingly require deeper drilling, work in more remote or complex terrain, or the identification of subtle surface expressions of buried systems that earlier exploration missed. The time from discovery to production — through resource definition, feasibility studies, permitting, and construction — typically spans a decade or more even when a project proceeds without major setbacks.
Conclusion
Copper’s geology is central to its economics. The concentration of supply in Chile, the DRC, and Peru reflects the specific tectonic settings where large copper deposits form, and the difficulty of finding and developing new deposits of comparable scale is part of why supply is structurally challenged relative to anticipated demand.
For investors following copper exploration companies, understanding what porphyry systems are, where they occur, and what exploration success actually looks like provides a more grounded basis for evaluating project announcements and assessing where a company’s ground sits within the broader geological picture.
Write to Tyler Jefferson at Mining.com.au
Images: Wikimedia Commons