


Robert Gregory is a man who’s built an enviable reputation as a stock picker.
His boutique firm, Glenmore Asset Management, specialises in the mid- to small-cap sector on the ASX.
Glenmore has a flexible mandate. Robert is willing to invest in the resource sector. Many other similar fund managers don’t.
Perhaps even more surprising is that the Glenmore fund isn’t averse to investing in coal.
The hot ‘thematics’ in resources right now are lithium, gold, and copper. The bigger industries of iron ore and coal don’t come up in the conversation much.
What coal and iron ore still do have, though, is profits.
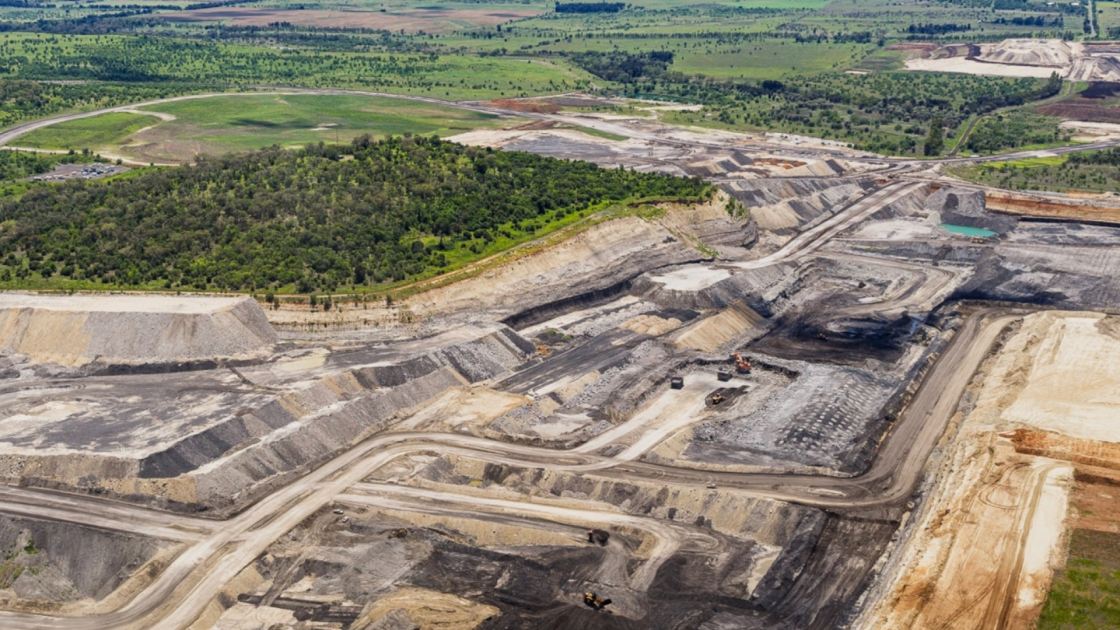
2026 has been interesting for New Hope (ASX:NHC). It operates two Australian thermal coal mines.
The stock was recovering in the first two months of the year before an unexpected development.
That was the Iran conflict breaking out. Of course, suddenly 20% of the world’s oil supply came under pressure. We know Brent oil futures hit as high as US$126 ($182) per barrel.
While coal supply wasn’t affected in the same way, the Hormuz closure still led to a rally in coal stocks.
There were echoes of 2022 when coal shares performed strongly after the Russian invasion of Ukraine.
Countries in Asia switched back to coal as LNG supplies out of Qatar were blocked.
New Hope rallied strongly to above $6 per share by 30 March.

The stock has been volatile since the Iran news began pushing energy traders around like a yo-yo.
It’s probably best to not emphasise an uncertain macro dynamic with NHC and look at the basic fundamentals of the coal market.
Robert Gregory told Livewire recently:
“In looking at consensus forecasts for the thermal coal price, most broking firms and investment banks have quite conservative prices factored into their earnings forecasts. Currently, the spot thermal coal price is ~US$140/t, whilst consensus forecasts for the next three years are more in the range of US$100/t to US$120/t.
“Whilst in the very long term it is reasonable to assume thermal coal’s share of the energy mix declines, we believe it is likely to remain a key source of base load power for at least the next five to 10 years. Given the lack of meaningful supply globally, combined with steady demand (particularly from Asia), a rally in prices from current levels would not be a surprise.”
Robert is not alone in thinking along these lines. Rystad Energy reported earlier this month that the loss of LNG supply from the Middle East could see an additional 150 million tonnes in thermal coal consumption by 2030.
The analyst notes:
“Until storage, grid flexibility, and firm low-carbon capacity scale sufficiently to cover peak demand and periods of low wind or hydro output, coal will continue to serve as the system’s fallback.”
While thermal coal may not surge like in 2022, pricing should be enough for NHC to make good money.
Stockopedia says the earnings per share growth in FY27 could be as high as 86% and the firm pays a 5% yield.
Please note that this is an observation, and not a recommendation for NHC.
Coal could be an interesting and surprising sector to watch in FY27.
Write to Callum Newman at Mining.com.au
Images: New Hope Coal & Optuma


